

Upgrade analysis by Appwee
I approached Upgrade as a finance app for people who want several money tools in one place rather than a single-purpose budgeting tracker. Its focus is personal loans, cards, and rewards checking, so the experience is more closely tied to borrowing and everyday account management than to manually categorizing every coffee or grocery purchase. That distinction matters: I would not choose it simply because I wanted a colorful spending diary.
The app is developed by Upgrade, Inc., and it is free to install for everyone. It has built a sizeable audience, with over a million installs, an average rating of 4.4 from around thirty thousand ratings, and roughly four thousand written reviews. Those figures suggest that many people find the combined approach useful, but they should not replace careful reading of the terms shown for an individual financial product. A finance app can be easy to use while the underlying decision still deserves patience.
How Upgrade Builds Trust Around Financial Decisions
A finance app that asks for more attention than a normal utility
My first impression is that Upgrade sits in a sensitive part of the app market. A notes app can be deleted after a disappointing session; a loan or card decision can affect a person’s monthly obligations. I therefore judge it less by visual polish and more by whether the user can understand what is being requested, review choices before committing, and keep control of the account afterward.
That is also why the developer matters here. Upgrade, Inc. is clearly identified as the company behind the app, rather than the product being presented as an anonymous comparison tool. The app’s store category is Finance, its content rating is Everyone, and its current version is 1.33.0. It was released on March 21, 2019, and requires iOS or Android version 12 or later. The operating-system requirement is worth checking before planning to use it on an older phone.
The free download is convenient, but “free” should be read as an access condition, not as a promise that every financial product inside the app has no cost. When I use an app connected with credit or borrowing, I treat the download as the beginning of the review process. I still inspect the details presented for the specific offer, including repayment information and any applicable conditions, before accepting anything.
What the combined design is good at
The central strength is concentration. Instead of moving between a loan marketplace, a card provider, and a separate checking application, a user can begin with one account and explore related money products from there. That can reduce the friction of remembering several logins and make it easier to review a broader financial picture.
There is a trade-off, though. A single provider may feel simpler, but simplicity can make a product ecosystem seem more uniform than it really is. Personal loans, cards, and rewards checking serve different purposes and may involve different terms. I would keep those decisions mentally separate even when the app puts them beside one another.
For someone trying to organize a short-term need, compare available choices, or manage an account connected with Upgrade, this structure is practical. For someone who wants an independent view across many banks and lenders, a traditional comparison service may be better. The app is most useful when its integrated approach matches the user’s goal, not merely because it offers several tabs.
Controls I would check before entering sensitive details
My advice is to treat every application screen involving identity, income, banking information, or credit as a checkpoint. Read the purpose of the request, confirm that the information is relevant to the action you are taking, and avoid rushing through a consent screen simply to reach the next page. This is especially important when the app moves from general browsing into an application or account setup.
I would also review the account and privacy controls available on the device and inside the app, then revisit them after setup. The useful question is not only “Can I open an account?” but also “Can I understand what I agreed to, change my choices later, and close or secure access if my phone changes hands?” Those checks give the user more agency than relying on a familiar brand name alone.
A practical habit is to capture the important terms for your own records before accepting an offer, without storing sensitive credentials in an unsafe place. That makes later comparison easier and helps prevent the common mistake of remembering only the attractive headline while forgetting the repayment structure or account conditions.
Where data sensitivity becomes most important
The most sensitive moments are not necessarily the ordinary dashboard visits. They are the transitions: starting a loan application, connecting a financial account, verifying identity, requesting a card, or changing account access. At those points, I slow down and look for clear explanations of why information is needed and what action the button will trigger.
I also avoid evaluating the app while distracted. A person checking a balance on a bus may be comfortable with a quick glance, but applying for credit in the same rushed state is a different matter. A better workflow is to use the app for browsing first, list the questions that remain, and return when there is enough time to read each screen.
On a shared or borrowed phone, I would be particularly careful. I would sign out when appropriate, protect the device with its own lock, and avoid leaving account pages open. These are simple habits, but they matter more for a finance app than for a weather or recipe application.
An everyday scenario where the app makes sense
Imagine that I want to replace a failing appliance and need to understand whether a personal loan is realistic, while also wanting a checking option for everyday spending. Upgrade’s combined setup gives me one place to explore those possibilities. I can begin by clarifying the amount I actually need, compare the repayment commitment with my monthly budget, and only then decide whether continuing is sensible.
The important part of that workflow is separation. I would not assume that opening or exploring a checking product automatically makes a loan appropriate. I would write down the total monthly obligation I can manage, leave room for utilities and unexpected expenses, and compare the result with alternatives from my existing bank or a credit union. The app can support the research stage, but it should not replace that personal calculation.
Another realistic use is account administration after choosing a product. Having related services in one application may make routine checking more convenient than switching among providers. Still, I would periodically review statements and account activity rather than relying on notifications or a quick balance glance. Convenience is helpful only when it does not reduce attention.
Who will appreciate it, and who should look elsewhere
I think Upgrade is a strong fit for an adult who wants a straightforward starting point for personal loans, card options, and rewards checking, especially if keeping related services together is more valuable than shopping across many providers. It may also suit someone who prefers handling financial tasks from a phone and is willing to read terms carefully instead of treating the app as an automatic recommendation engine.
I would be more cautious if you are already struggling with debt, are tempted by available credit, or need highly specialized budgeting tools. In those situations, a nonprofit financial counselor, an established bank relationship, or a dedicated budgeting app may provide a better foundation. A consolidated finance app can make access easier, but easier access is not always the same as healthier borrowing.
It is also not my first choice for someone whose main goal is detailed household budgeting. If you want extensive manual categories, long-term spending analysis, or a broad view of accounts from many unrelated institutions, a dedicated money-management service may be more suitable. Upgrade’s identity is centered on financial products and account use, not on replacing every budgeting method.
How it compares with familiar alternatives
Compared with using a conventional bank, Upgrade may feel more focused on bringing borrowing, card use, and checking into one experience. A conventional bank may be preferable if you already have trusted support, established account history, or a wider range of services there. The better choice depends on whether consolidation or continuity matters more in your situation.
Compared with a standalone loan comparison service, Upgrade offers a more direct relationship with its own product environment. That can be less overwhelming, but it also means I would not treat the app as a complete view of the market. I would compare the relevant terms with other legitimate options before making a commitment, particularly for a large or long-running obligation.
Compared with a budgeting app, the difference is even clearer. Budgeting software generally starts with spending visibility and planning; Upgrade starts with products and account access. Someone who needs help deciding where every paycheck goes may get more value from a budgeting-first tool, while someone exploring a loan or checking relationship may prefer Upgrade’s narrower focus.
Small habits that improve the experience
Use the app first as a research space. Write down the purpose of a loan or account before entering an application flow, so the available product does not define the need for you.
Review one financial product at a time. Keeping loan, card, and checking questions separate makes it easier to notice which terms belong to which decision.
Check the account after important changes. A quick review of activity, contact details, and security settings can catch mistakes earlier than waiting for a problem to become urgent.
Keep alternatives visible. Even if Upgrade is convenient, compare the relevant offer with your bank, credit union, or another suitable provider before accepting a significant commitment.
What I would want a new user to understand
The app does not remove the need for financial judgment. Its value is in giving a user a focused place to explore several connected services, not in deciding whether borrowing is wise. I would approach it with a written purpose, a realistic monthly limit, and enough time to read every important screen.
I would also make sure the phone meets the minimum operating-system requirement before downloading. If it does not, the practical solution is not to force the installation but to use a supported device or choose another way to manage the financial task. Keeping the operating system current is sensible for any app handling personal information.
Because the app is rated for Everyone, families may see it as broadly accessible, but financial suitability is still personal. An age label describes the content classification; it does not mean every loan, card, or checking decision is appropriate for every person. I would keep that distinction clear when recommending it to someone else.
My cautious verdict
After looking at Upgrade through the lens of control and trust, I see a useful finance app with a clear niche. Its combination of personal loans, cards, and rewards checking can save time for users who want a connected experience, and the free installation makes it easy to investigate without committing immediately. The established developer and substantial user base provide context, but they are not substitutes for reading product terms or protecting account access.
My recommendation is conditional but positive: try it if you want to explore these particular services in one place and you are comfortable taking responsibility for each decision. Use the app slowly at sensitive moments, review the choices presented, and compare meaningful offers elsewhere. The best feature here is not convenience alone; it is the ability to make a deliberate decision before convenience turns into an obligation.
I would skip it when the real need is independent market comparison, detailed budgeting, or debt counseling. In those cases, another type of service is likely to serve you better. For the right user, however, Upgrade is a practical starting point for managing borrowing and everyday financial products from a phone, provided that the user remains actively involved in the choices.
Gallery
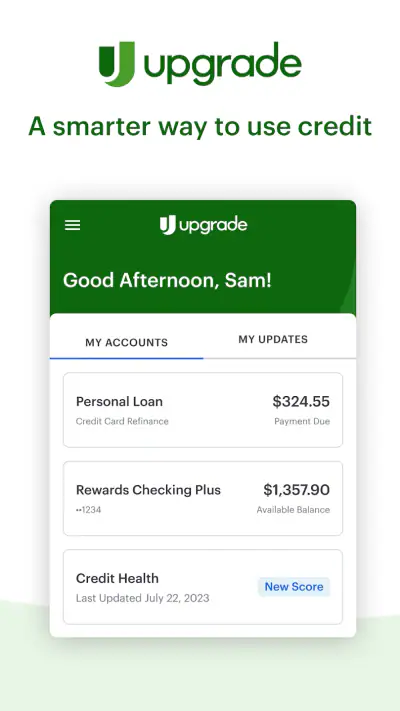
Upgrade Pros and Cons
- Simple interface makes account upgrades easy to find and manage.
- Clear status updates help users track upgrade progress.
- Useful reminders can reduce the chance of missing important deadlines.
- Supports faster access to features after an upgrade is completed.
- Convenient for managing upgrade-related tasks from a mobile device.
- Some upgrade options may depend on your account or service provider.
- Notifications could become excessive if several reminders are enabled.
- The app may offer limited help when an upgrade fails or is delayed.
- Certain features might require an active internet connection.
- Upgrade details may vary by region
- plan
- or device compatibility.
Upgrade Frequently Asked Questions
What is Upgrade, and what can I use it for?
Upgrade is a financial services app designed to help users manage personal finances through products such as checking-style accounts, cards, loans, and credit-building tools, depending on eligibility and location. After installing it, you can review available offers, monitor transactions, make payments, and access account information from one place. Features may vary by region and applicant profile.
Is Upgrade a bank, and is my money protected?
Upgrade provides financial products through partner institutions rather than functioning as a traditional bank in every aspect. Some accounts may be provided by an FDIC-insured partner, while card and lending services have separate terms and protections. Before depositing money or applying for a product, carefully check the in-app disclosures to understand insurance coverage, fees, eligibility, and which company provides each service.
Can I apply for an Upgrade card or personal loan directly from the app?
Yes, eligible users can generally explore applications for Upgrade products from within the app. The process may include identity verification, a credit check, income information, and other approval requirements. Prequalification, when available, does not guarantee approval or final terms. Interest rates, credit limits, repayment periods, and fees depend on your credit profile and the specific offer.
Are there fees or interest charges when using Upgrade?
Upgrade products can involve different costs, including interest charges, annual or other account fees, late-payment fees, loan origination fees, or fees associated with specific services. The exact charges depend on the product and your agreement. I recommend reviewing the pricing information and full terms before accepting an offer, rather than relying only on promotional descriptions shown during the application process.
Is Upgrade safe to use, and what information does it require?
Upgrade uses account security measures such as login protection, identity verification, and encrypted connections, but no financial app can eliminate every security risk. The app may request personal, employment, income, and banking information to verify your identity or evaluate applications. Download it only from an official app store, use a strong unique password, enable available security features, and contact official support if you notice suspicious activity.














